
U.S. equity markets head into the week with cautious optimism, as investors balance encouraging earnings signals against a backdrop of rising energy prices and evolving macroeconomic conditions. After a period of volatility earlier in the quarter, major indexes have stabilized, supported in part by stronger-than-anticipated corporate results. However, the sustainability of the rally now hinges on whether upcoming economic data and earnings reports reinforce confidence in the economic outlook.
One of the central variables shaping investor sentiment is the recent surge in oil prices. Crude benchmarks have climbed to multi-week highs, reflecting a combination of supply constraints and geopolitical risks. Higher energy costs have historically posed challenges for equity markets, particularly by increasing input costs for businesses and reducing discretionary income for consumers. Analysts note that while energy sector stocks may benefit from higher prices, the broader market could face headwinds if inflationary pressures intensify.
Market participants are closely monitoring whether rising oil prices will feed through to broader inflation measures. If inflation shows signs of reaccelerating, it could complicate the Federal Reserve’s efforts to maintain a balanced policy stance. While recent data suggested inflation was moderating, a renewed uptick could prompt policymakers to keep interest rates elevated for longer than previously expected. This scenario would have implications for equity valuations, particularly in interest-rate-sensitive sectors such as technology and real estate.
At the same time, corporate earnings remain a key pillar supporting the market. Several large-cap companies have reported results that exceeded expectations, highlighting resilience in areas such as consumer spending and enterprise investment. However, investors are paying close attention not only to headline numbers but also to forward guidance. Companies’ commentary on cost pressures, pricing power, and demand trends will be critical in assessing whether earnings growth can be sustained in the face of rising input costs.
The upcoming wave of earnings reports is expected to provide further clarity across sectors. Retailers, manufacturers, and service providers will offer insights into consumer behavior and supply chain conditions. In particular, any indications that higher fuel costs are being passed on to consumers—or absorbed by companies—could influence sector performance. Analysts suggest that divergence between sectors may widen, with energy and certain industrial firms outperforming, while consumer-facing businesses face more scrutiny.

The labor market also remains a focal point. The release of the latest U.S. jobs report later in the week is expected to provide a comprehensive snapshot of employment conditions. Economists are watching for signs of either continued strength or gradual cooling. A robust labor market would reinforce the narrative of economic resilience but could also sustain wage pressures, potentially feeding into inflation. Conversely, evidence of softening employment conditions could ease inflation concerns but raise questions about economic momentum.
Investors are particularly attentive to wage growth data, as it plays a critical role in shaping inflation expectations. If wage increases remain elevated, it could signal persistent inflationary pressure, complicating the Federal Reserve’s policy outlook. On the other hand, a moderation in wage growth could support the case for a more stable or even accommodative monetary stance later in the year.
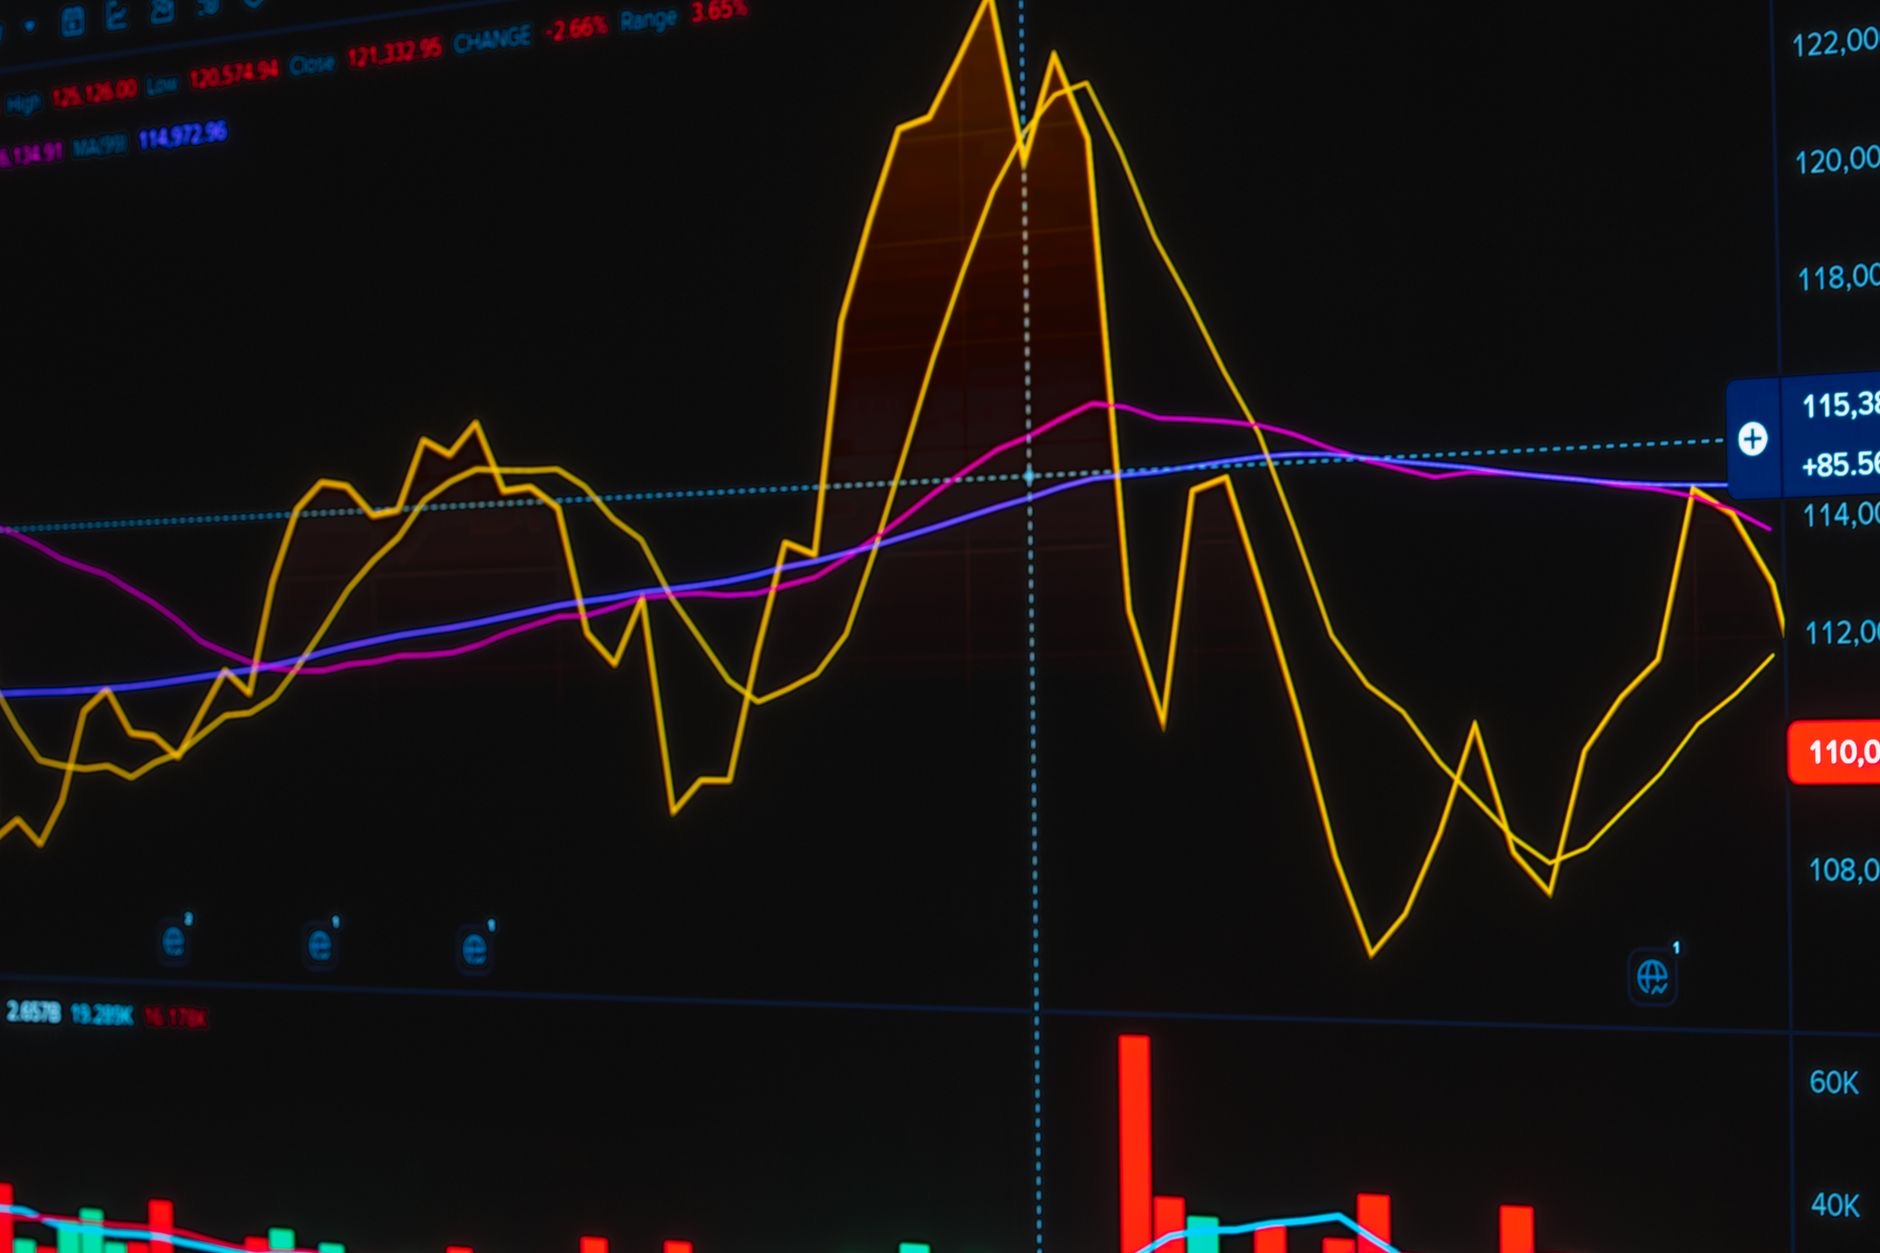
Beyond macroeconomic indicators, broader market dynamics are also influencing sentiment. Trading volumes and volatility measures suggest that investors are positioning cautiously, with some adopting a wait-and-see approach ahead of key data releases. Options market activity indicates increased hedging, reflecting uncertainty about near-term market direction.
Institutional investors are also reassessing sector allocations. The rise in oil prices has prompted renewed interest in energy stocks, which had underperformed earlier in the year. At the same time, technology stocks continue to attract attention due to their growth potential, although they remain sensitive to interest rate expectations. Financial stocks, meanwhile, are influenced by both interest rate trends and broader economic conditions.
Global factors are adding another layer of complexity. Developments in international energy markets and geopolitical tensions are contributing to oil price volatility, with potential spillover effects on U.S. markets. Additionally, currency movements and global economic data could influence capital flows and investor sentiment.
Despite these uncertainties, some market strategists remain cautiously optimistic. They point to the underlying strength of corporate balance sheets and continued consumer spending as factors that could support the market. However, they also emphasize that the margin for error is narrowing, particularly if inflationary pressures intensify or economic data disappoints.
Looking ahead, the convergence of earnings reports, economic data, and commodity price movements is likely to define the market narrative. Investors will be parsing each data point for clues about the trajectory of growth, inflation, and monetary policy. The outcome of this week’s developments could set the tone for markets in the coming months, influencing everything from asset allocation decisions to risk appetite.
In the near term, volatility is expected to remain elevated as markets react to incoming information. While the recent rally has provided some momentum, sustaining it will require a delicate balance of positive earnings surprises, stable inflation trends, and supportive economic data. As such, the week ahead represents a critical test for the resilience of U.S. equities in an increasingly complex macroeconomic environment.
Leave a Reply