
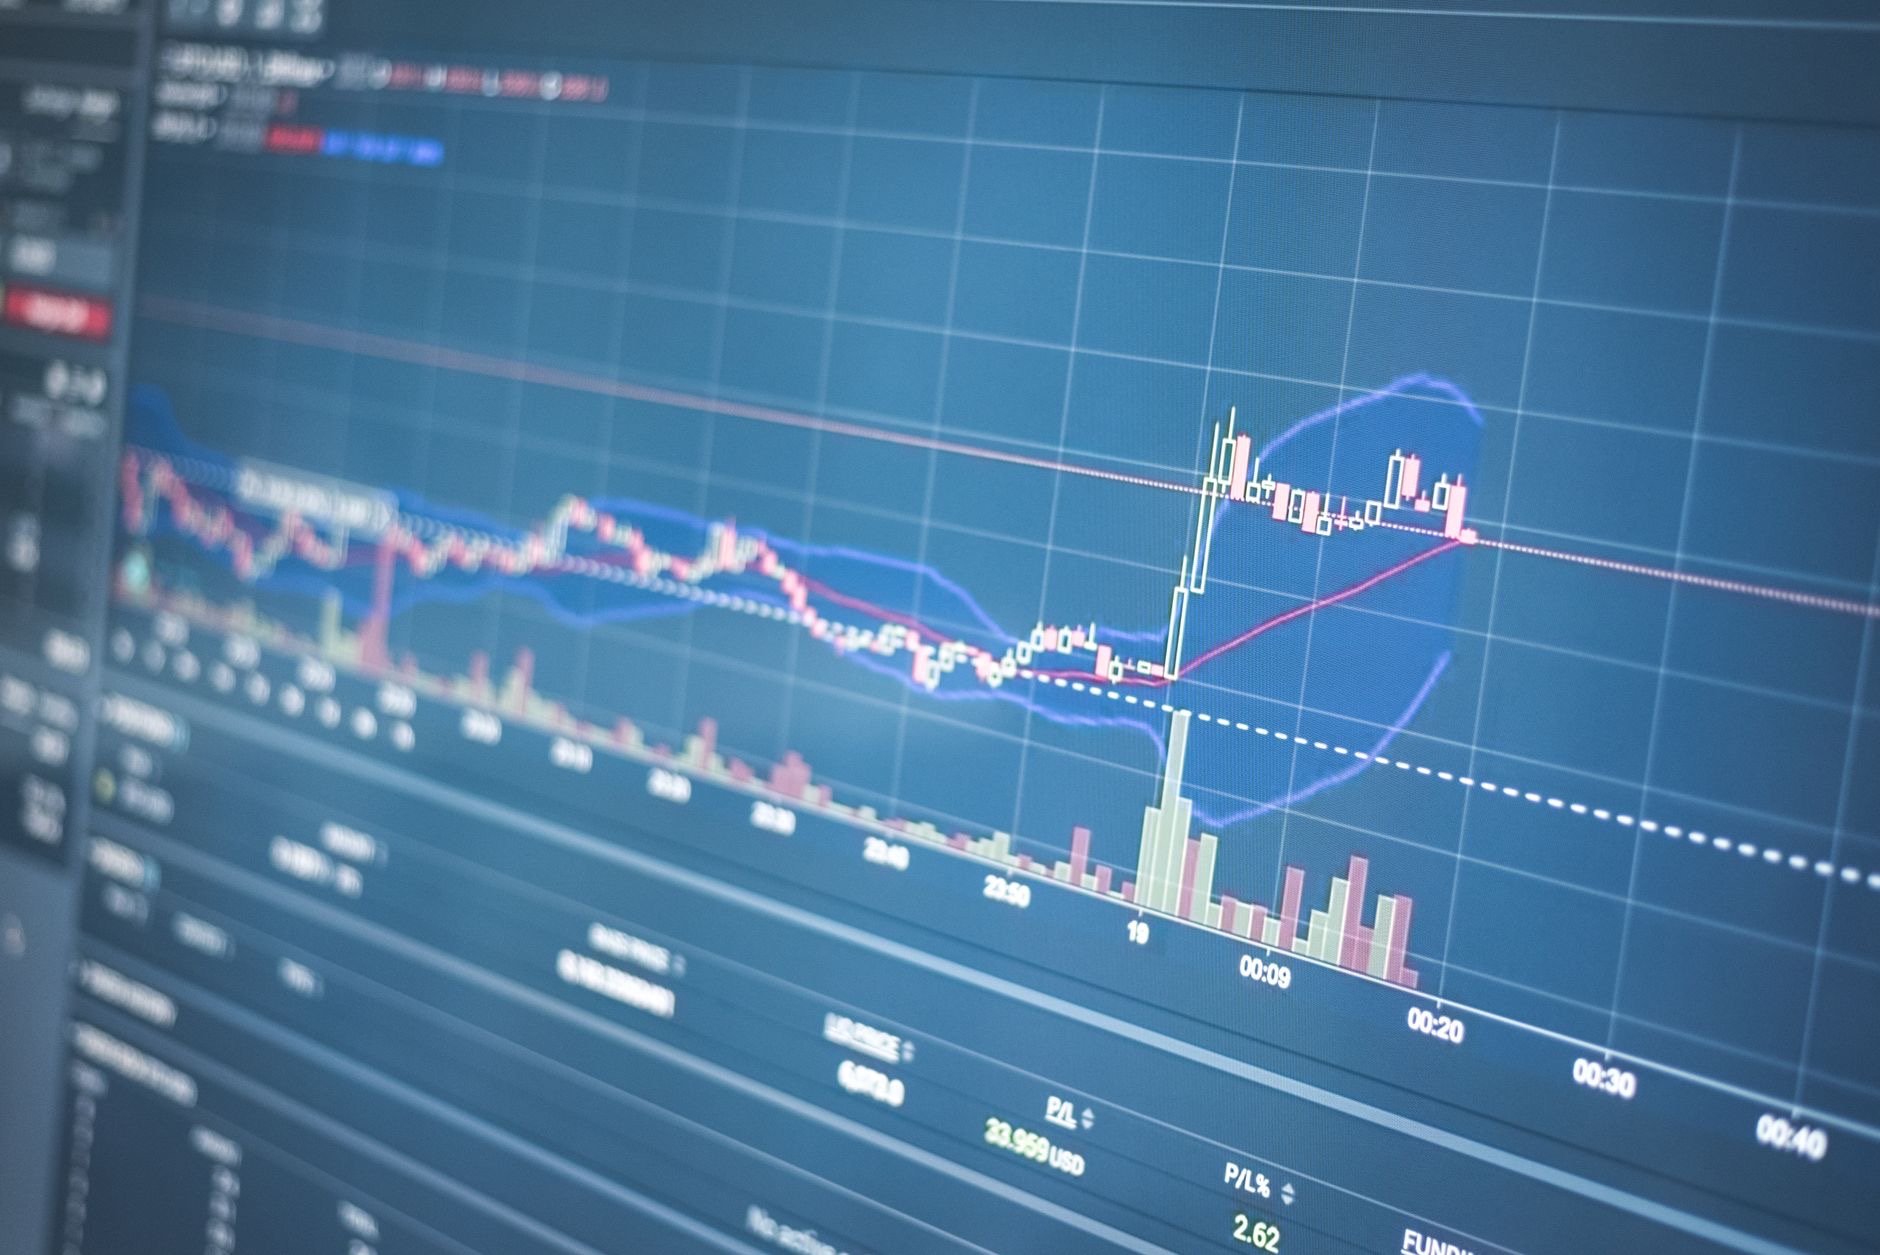
The Dow Jones Industrial Average ended November 20, 2026, at 48,147.33 after an 8% weekly plunge wiped approximately 4,200 points from the blue-chip index, leaving Wall Street confronting a more uncertain outlook for stocks in 2027. Friday’s session alone produced a 949.73-point decline, equivalent to 1.93%, as investors continued reducing exposure to technology, financial and industrial companies.
The selloff placed the Dow approximately 11.4% below its August 5 record closing high of 54,349.12, meeting the commonly used definition of a market correction. The index also broke below the psychologically significant 50,000 level during the week, indicating how rapidly investor sentiment had deteriorated. Although the Dow fell less sharply than technology-heavy benchmarks, its losses demonstrated that the retreat was no longer confined to artificial intelligence shares.
The broader market suffered even greater damage. The S&P 500 declined 8.6% for the week, finishing Friday at 6,910.39 after dropping 3.7% during the final session. The Nasdaq Composite fell approximately 10% over five trading days and closed at 22,617.73, erasing its gains for 2026. According to the Associated Press, the S&P 500 recorded its steepest weekly decline since April 2025.
Those figures established a difficult starting point for investors assessing the next calendar year. Before the latest selloff, several major financial institutions had published forecasts anticipating continued gains for American equities in 2027. Their projections generally depended on resilient corporate earnings, sustained investment spending and an economy capable of absorbing relatively elevated interest rates. Friday’s closing levels increased the importance of determining whether those assumptions remain realistic.
Goldman Sachs provided one of the clearest examples of that optimistic outlook. In research published November 19, the firm projected that the S&P 500 would reach 8,700 by the end of 2027, implying an anticipated total return of approximately 18% over the forecast horizon used in its analysis. The firm’s strategists expected positive but slower corporate profit growth to remain the primary driver of equity performance.
Importantly, Goldman Sachs’ target applies to the S&P 500 rather than the Dow Jones Industrial Average. The two benchmarks differ significantly in their construction and sector exposure. The S&P 500 weights companies primarily by market capitalization, while the Dow is a price-weighted index comprising 30 major American companies. Consequently, an S&P 500 target cannot be translated directly into a reliable Dow closing-level prediction.
Goldman Sachs expects S&P 500 earnings growth to slow to approximately 11% in 2027, compared with roughly 30% in 2026. Its analysis suggests that future stock gains will increasingly depend on actual profit expansion rather than investors paying higher valuation multiples. Elevated borrowing costs, uncertainty surrounding artificial intelligence investment and slower earnings growth could limit the potential for broad increases in price-to-earnings ratios.
That distinction is especially important following the November market correction. Lower stock prices can make valuations less demanding, but they do not automatically establish that shares are inexpensive relative to their future earnings. If corporate profit forecasts deteriorate alongside stock prices, valuation measures may remain elevated. A sustainable recovery would therefore require evidence that company earnings are holding up despite the decline in market confidence.

Artificial intelligence investment remains one of the largest uncertainties affecting that calculation. Spending on data centers, advanced semiconductors, electricity infrastructure and cloud computing has supported earnings growth across multiple industries. However, investors are increasingly questioning whether the companies financing that expansion will generate sufficient revenue and profits to justify their substantial capital commitments.
Goldman Sachs estimates that AI-related capital expenditure contributed approximately half of S&P 500 earnings-per-share growth in 2026. The firm expects that contribution to moderate next year as the pace of investment expansion slows and depreciation expenses increase. Its analysis also identifies weaker expectations for 2028 earnings as a major downside risk to stock valuations during 2027.
The implications extend beyond Silicon Valley. Manufacturers supplying equipment, electrical systems, industrial machinery and construction services have benefited from infrastructure investment associated with AI development. A reduction in planned projects could weaken order growth and revenue expectations throughout those supply chains. For Dow constituents with significant industrial exposure, changes in investment commitments may become as important as the financial performance of technology companies themselves.
Financial stocks face a different combination of pressures. Higher interest rates can support certain lending margins, but prolonged borrowing costs may also reduce loan demand, limit corporate acquisitions and constrain investment activity. Sharp equity-market declines can additionally affect wealth management, underwriting and trading businesses. During Friday’s selloff, Goldman Sachs shares fell approximately 6.7%, contributing substantially to the Dow’s decline because of the index’s price-weighted structure.
Not all Dow components experienced the same degree of pressure. Walmart, UnitedHealth Group and Verizon advanced during Friday’s trading, demonstrating continued demand for some companies with relatively defensive business characteristics. Walmart gained approximately 1.5%, while UnitedHealth rose about 2.8%. The divergence suggested that investors were becoming more selective about earnings predictability, balance-sheet strength and exposure to economically sensitive investment spending.
Federal Reserve policy represents another major consideration for the 2027 outlook. Minutes from the central bank’s October 27-28 meeting, released November 18, showed that policymakers had maintained the federal funds target range at 3.75% to 4%. Two officials preferred an increase of 25 basis points, reflecting continuing concerns about inflation and the appropriate degree of monetary restraint.
The minutes also documented explicit concerns about vulnerabilities associated with AI financing. Federal Reserve staff highlighted rapid growth in debt related to artificial intelligence infrastructure, including complex financing arrangements that could amplify losses if investment returns disappointed. Policymakers also discussed the potential for declining asset prices to trigger additional selling by leveraged investors and investment funds.
Those concerns have become particularly relevant as markets approach the Federal Reserve’s December 8-9 policy meeting. Additional monetary tightening could increase financing costs for businesses and consumers, while also affecting the valuations investors assign to future corporate earnings. Conversely, evidence of moderating inflation or weaker economic activity could change expectations for the interest-rate path. The direction of policy will remain central to market forecasts for 2027.

Bond-market movements already illustrate the tension between inflation concerns and worries about economic growth. The yield on the benchmark 10-year U.S. Treasury note declined to approximately 4.93% on Friday from 5.04% on Thursday, according to Associated Press market reporting. Falling yields can eventually support equity valuations, but they may also reflect investors seeking relatively safer assets during periods of market stress.
The Dow’s immediate technical position has also deteriorated. Friday’s close near 48,147 left the index close to the 48,000 level, which it briefly breached during the session. A sustained recovery above recent trading ranges would indicate improving demand for blue-chip shares. However, a temporary rebound following heavy selling would not necessarily demonstrate that the broader correction had ended.
Market history offers context without providing a definitive prediction. In a November 21 analysis, the Associated Press cited CFRA research showing that 25 S&P 500 corrections since 1946 that avoided becoming bear markets took an average of 130 days to reach their lows. Their average peak-to-trough decline was approximately 14.1%. Declines that developed into bear markets were considerably more severe, underscoring the uncertainty surrounding any individual correction.
The distinction matters because the Dow’s 8% weekly loss, while substantial, does not establish what will happen over the next several months. Market rebounds can begin before economic conditions visibly improve, but downturns can also continue when earnings expectations weaken, financing conditions tighten or investors reassess the prices they are willing to pay for future growth.
The next round of economic releases will provide additional evidence about those risks. November purchasing managers’ indexes are scheduled for November 23, followed by important U.S. economic data, including personal consumption expenditures inflation figures, on November 25. Investors will examine whether business activity, prices and consumer spending are consistent with the earnings assumptions underlying current equity forecasts.
For 2027, the most consequential development may be whether corporate earnings growth broadens beyond the companies directly benefiting from AI infrastructure spending. Financial institutions, industrial manufacturers, healthcare providers and consumer businesses will need to demonstrate sufficient profitability to support a more balanced market recovery. Without broader earnings participation, major indexes could remain vulnerable to changes in a relatively small number of influential companies.
The Dow enters the final weeks of 2026 facing a considerably different environment from the one reflected in earlier optimistic market forecasts. Goldman Sachs continues to anticipate positive returns through 2027, but the November correction has made the path toward those expectations more uncertain. Whether the Dow stabilizes or declines further will depend on incoming evidence about corporate earnings, monetary policy, borrowing conditions and the economic returns generated by America’s enormous investment in artificial intelligence.
Leave a Reply