
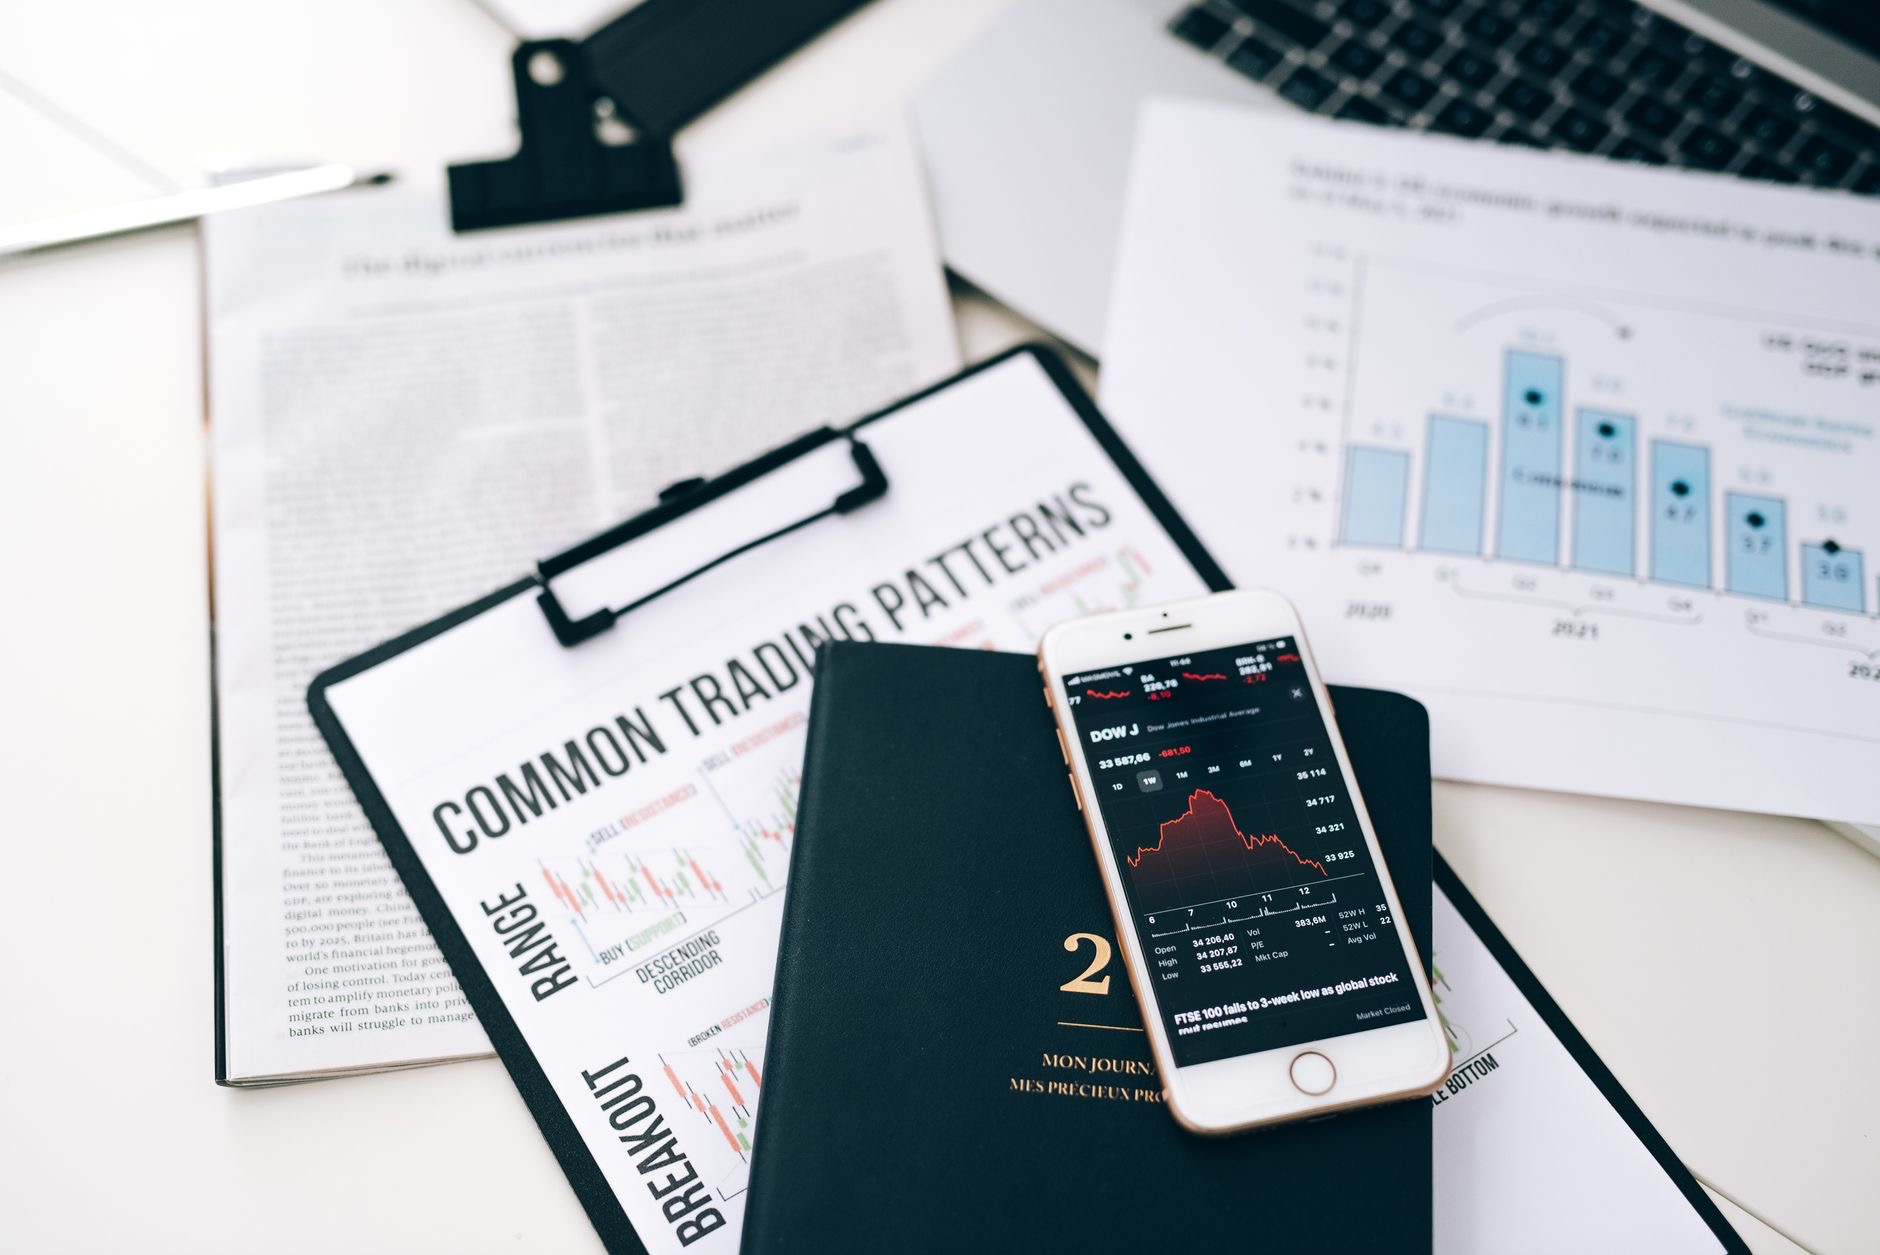
U.S. stock index futures edged higher on Monday, November 2, as investors entered a closely watched week of manufacturing and employment data following a sharp October selloff in technology shares. S&P 500 futures gained approximately 0.4% in early trading, while Dow Jones Industrial Average futures rose 0.4% and Nasdaq-100 futures advanced around 0.8%, according to Yahoo Finance. The positive opening outlook reflected tentative buying interest after recent losses, although market participants remained focused on the sustainability of economic growth and corporate earnings.
The early advance came after Wall Street suffered significant losses in the final trading session of October. On Friday, the S&P 500 dropped 1.82%, the Dow declined approximately 1.09% and the Nasdaq Composite fell 2.86%. Technology and semiconductor stocks were among the hardest hit as concerns intensified over the scale of artificial-intelligence infrastructure investment and the financial returns companies could generate from those expenditures.
The Nasdaq Composite lost approximately 5.3% during October, according to Reuters, reflecting a broader reassessment of valuations in technology companies. Monday’s initial recovery suggested that some investors considered the recent selling excessive, but the market’s subsequent fluctuations showed that confidence had not fully returned.
The Institute for Supply Management provided the first major economic development of the week when it released its October manufacturing survey at 10 a.m. Eastern Time. The headline Manufacturing Purchasing Managers’ Index increased to 55.5 from September’s 54.5, exceeding the 54.7 consensus estimate listed in TD Economics’ economic calendar.
The report marked the tenth consecutive month of expansion in U.S. manufacturing activity. Readings above 50 generally indicate expansion, while readings below that level suggest contraction. The October result showed that manufacturing growth accelerated despite persistent uncertainty surrounding input costs, international trade and supply-chain conditions.
Several components of the survey pointed toward stronger industrial activity. The New Orders Index increased to 55.5 from 55.3, while the Production Index climbed to 59.0 from 56.7. The production reading was the highest since November 2021, according to ISM.
Manufacturing inventories also returned to expansion territory, with the Inventories Index increasing to 51.4 from 48.6. New export orders rose modestly, and the Imports Index improved to 52.9 from 51.0. Together, the figures indicated that demand and production remained relatively resilient across significant portions of the manufacturing economy.
For industrial companies, stronger manufacturing activity can signal opportunities for higher production volumes and improved revenue. Machinery manufacturers, transportation-equipment producers, chemical companies and suppliers of electronic components are among the businesses whose financial performance may be influenced by changes in factory orders and capital investment.
However, the latest manufacturing figures also highlighted continuing cost pressures. ISM’s Prices Index declined to 75.2 from 77.9, indicating that raw-material prices continued increasing, although at a slower pace. The elevated reading suggested that inflationary pressures affecting manufacturers had not disappeared.
The distinction between slowing price increases and falling prices is important for investors. A lower prices index may indicate that cost pressures are becoming less intense, but manufacturers can still face higher expenses that affect profit margins and ultimately consumer prices.
Manufacturing employment provided another mixed signal. The ISM Employment Index registered 52.4 in October, down from 52.7 in September. Although the measure remained in expansion territory, the decline indicated that hiring growth in the manufacturing sector had moderated.

The employment component carries particular importance because investors are preparing for additional labor-market information throughout the week. Tuesday, November 3, brings the Bureau of Labor Statistics’ Job Openings and Labor Turnover Survey for September, which provides information about labor demand, hiring and employee separations.
Wednesday’s calendar includes the ADP National Employment Report for October, offering another perspective on private-sector hiring. The same day, ISM is scheduled to publish its services-sector purchasing managers’ index, providing additional evidence about business activity beyond manufacturing.
The week’s most closely watched employment release is scheduled for Friday, November 6, when the Bureau of Labor Statistics publishes its October Employment Situation report at 8:30 a.m. Eastern Time. That report will provide updated figures for nonfarm payroll growth, unemployment and wages.
The preceding September report showed that U.S. employers added 29,000 jobs while the unemployment rate stood at 4.2%. Those relatively modest payroll gains have increased attention on whether employers are becoming more cautious about expanding their workforces even as some measures of business activity remain positive.
For financial markets, the relationship between employment and inflation is central to expectations for Federal Reserve monetary policy. Stronger hiring can support household spending and corporate revenue, but it may also reduce the pressure for lower interest rates if economic demand remains firm and inflation persists.
Conversely, weaker hiring could increase expectations that policymakers will eventually adopt a more accommodative approach. The market reaction would depend partly on whether investors interpret softer employment figures as evidence of manageable economic cooling or a more substantial deterioration in growth.
Interest-rate expectations also affect different stock-market sectors unevenly. Technology companies with valuations heavily dependent on projected future earnings can be sensitive to changes in Treasury yields. Banks, real estate companies, utilities and highly indebted businesses may respond differently depending on the implications for borrowing costs, credit demand and economic activity.
Beyond economic data, investors were closely monitoring the technology sector following the previous week’s sharp declines. Artificial-intelligence spending remained a central concern, particularly as major technology companies continued investing heavily in data centers, specialized chips and computing infrastructure.
Reuters reported that investors were questioning whether the rapidly increasing costs of AI development would generate sufficiently strong returns. The market’s reassessment affected semiconductor manufacturers, cloud-computing companies and businesses exposed to large technology infrastructure projects.
Apple and Palantir Technologies were among the companies scheduled to release quarterly earnings after Monday’s closing bell. Their results were expected to provide additional information about consumer technology demand, enterprise software spending and corporate investment priorities.
Apple shares weakened during Monday’s session ahead of its results, while several other technology stocks experienced significant price swings. Nvidia reversed an early gain, according to the Associated Press, illustrating the continuing sensitivity of AI-related equities to changes in investor sentiment.
The broader market also responded to developments in energy prices. Crude oil fell sharply Monday amid growing hopes of diplomatic progress involving the United States and Iran. Lower oil prices can ease transportation and operating costs for many businesses and potentially reduce some inflationary pressures.
Airlines and cruise operators were among the companies benefiting from the decline in crude prices. The Associated Press reported gains in United Airlines, Southwest Airlines and Carnival during Monday’s trading session, demonstrating how lower energy costs can support industries with substantial fuel expenses.
Energy producers faced a different outlook because declining crude prices can reduce revenue expectations. The contrasting performance highlighted the importance of distinguishing between movements in broad market indexes and the financial conditions affecting individual industries.
Despite the favorable manufacturing report and lower energy prices, Wall Street’s early rally lost momentum as the trading day progressed. The Associated Press reported that the S&P 500 was virtually unchanged in late-afternoon trading after earlier climbing as much as 1.1%. The Dow remained higher while the Nasdaq moved into negative territory.
The reversal reflected continued pressure from major technology shares, even as a majority of S&P 500 constituents advanced. The difference between market breadth and index performance underscored the substantial influence of large technology companies on capitalization-weighted benchmarks.
Political developments added another layer of uncertainty. U.S. congressional midterm elections were scheduled for Tuesday, November 3, and investors were evaluating potential implications for fiscal policy, corporate regulation, taxation and federal spending. Election results could influence sector-specific expectations, although their ultimate market impact would depend on subsequent policy decisions.
The combination of manufacturing resilience, elevated input prices and uneven technology performance created a complicated backdrop for the beginning of November. Economic data suggested that industrial activity remained relatively strong, but questions about labor-market momentum and the profitability of large-scale technology investment continued to weigh on sentiment.
Investors now face several potential turning points. Upcoming job openings and payroll data will help clarify labor-market conditions, while corporate earnings will offer evidence about consumer demand, operating expenses and capital investment. Developments in energy markets and interest rates will provide additional signals about inflation expectations.
Monday’s trading demonstrated that favorable economic indicators alone may not be sufficient to stabilize U.S. equities when concerns about valuations and corporate spending remain unresolved. Whether the S&P 500 can sustain a recovery will depend on how investors interpret the next round of employment figures, company results and broader economic developments throughout the week.
Leave a Reply