
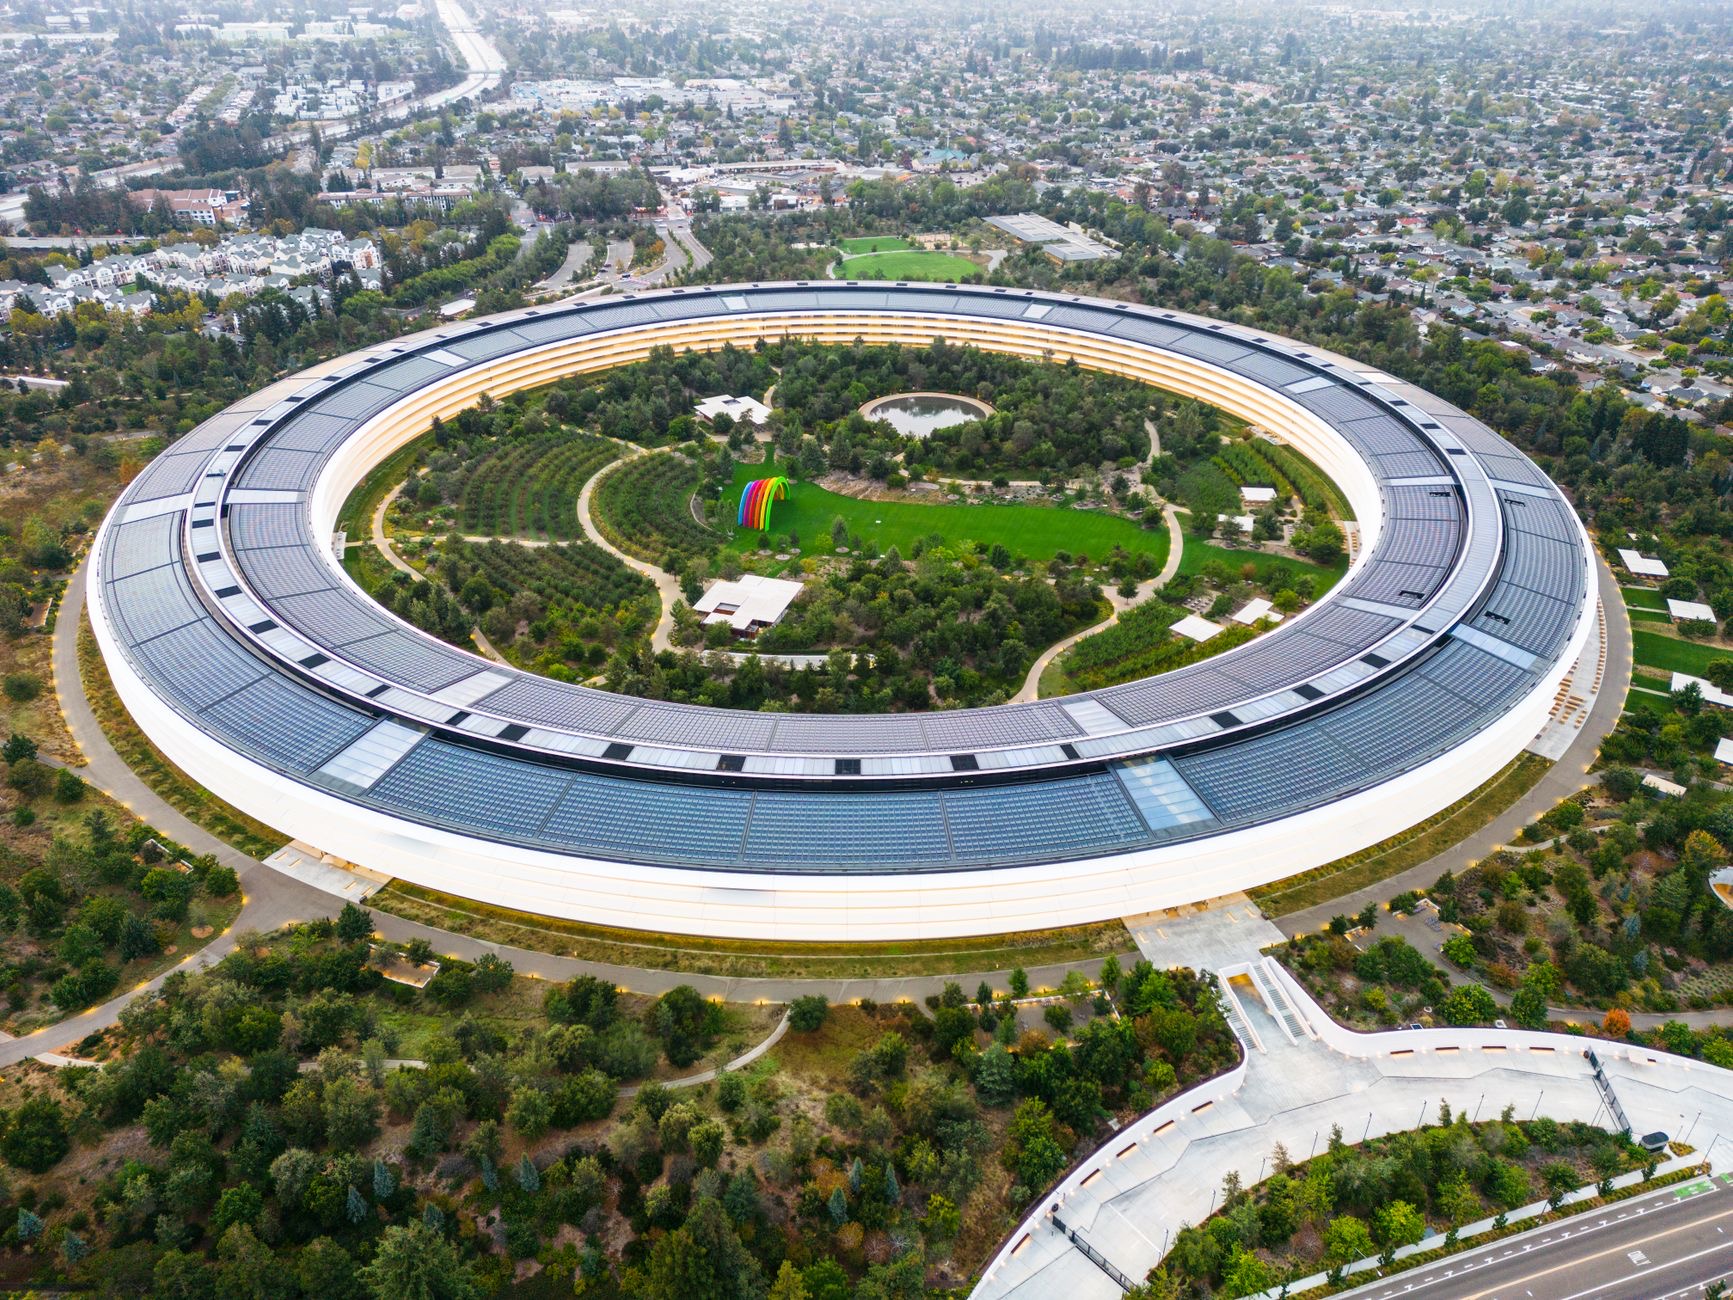
Apple’s refusal to follow its largest technology rivals into an unprecedented artificial-intelligence spending boom is winning new praise from Wall Street, but the strategy is approaching a more difficult test: delivering advanced AI products at global scale without owning comparable computing infrastructure.
HSBC analyst Nicolas Cote-Colisson upgraded Apple shares to “buy” from “hold” in a report published Friday, raising his price target to $366 from $260. The analyst argued that Apple’s restrained approach to AI spending could become a competitive advantage as investors grow more concerned about the capital intensity of the broader industry.
According to reports on the upgrade, Apple’s capital spending represents roughly 2.5% of estimated sales, compared with about 39% for major hyperscale computing companies. That gap has allowed Apple to preserve the cash-generating profile that historically distinguished it from other large technology companies.
The contrast is becoming more pronounced. Google, Amazon, Microsoft and Meta have outlined plans to spend more than $700 billion during 2026, largely to secure data-center capacity, accelerators, networking equipment and energy infrastructure. Those companies are trying to meet demand for AI training, cloud services and inference—the process of running completed models for users.
The cost of that expansion is also rising. Business Insider reported Saturday that Morgan Stanley estimates the price of building one gigawatt of AI capacity has increased about 20% for several prominent systems. One commonly deployed Nvidia-based configuration rose from roughly $29 billion to $35 billion per gigawatt, while a newer system increased from about $41 billion to $49 billion.
Apple has largely avoided that cycle. Rather than attempting to build the world’s largest foundational models or rent computing capacity to corporate customers, the company has concentrated on integrating AI into devices and software used by its existing customer base. Its strategy combines processing on Apple silicon with Private Cloud Compute servers for tasks that require more capacity.
That architecture offers financial and product advantages. On-device processing can reduce cloud usage, improve response times and keep sensitive information closer to the user. Apple also designs the chips, operating systems and consumer hardware on which its features run, allowing it to optimize smaller models for specific functions instead of relying exclusively on costly, general-purpose systems.

The company’s installed base gives it another potential advantage. Apple does not necessarily need to charge consumers directly for every AI query. Better software could support iPhone upgrades, strengthen customer loyalty and make the company’s services more valuable. Apple can also act as a distributor for outside AI providers seeking access to a vast population of high-spending users.
For now, investors appear increasingly receptive to that argument. Apple shares recently outperformed the broader market as analysts reconsidered whether the company’s slow entry into generative AI reflected a strategic failure or financial discipline. The stock’s rally has coincided with growing scrutiny of the effect that infrastructure spending is having on competitors’ free cash flow.
Apple’s own finances provide substantial room to maneuver. The company reported revenue of $111.2 billion for its fiscal second quarter ended March 28, an increase of 17% from a year earlier. It generated more than $28 billion in quarterly operating cash flow and authorized an additional $100 billion share-repurchase program.
Yet low capital spending does not eliminate the cost of AI. It can move that cost elsewhere. Capacity obtained from partners may appear as operating expenses rather than property and equipment. Access to outside models could involve licensing payments, minimum commitments or revenue sharing. Depending heavily on other companies may also limit Apple’s control over release schedules, pricing, reliability and product differentiation.
Apple could face additional pressure if AI assistants become the primary interface through which users search, shop, communicate and access applications. In that scenario, the company would need to ensure that Siri and Apple Intelligence remain central to the experience rather than becoming a thin layer directing users to competing platforms.
More capable assistants also require greater inference capacity. A simple writing tool or notification summary consumes relatively limited resources. An agent that continuously analyzes personal context, coordinates multiple applications, interprets images and performs complex tasks can require far more computation. Multiplied across hundreds of millions of active devices, even efficient models can create significant infrastructure costs.

Apple therefore has several possible bills ahead. It may need to add Private Cloud Compute capacity, buy more advanced servers, expand data-center leases or secure additional supplies of high-bandwidth memory and networking components. It could increase research-and-development spending to build stronger proprietary models, or acquire AI companies with technology and engineering talent that would take years to develop internally.
The timing matters because equipment and construction costs are already elevated. By waiting, Apple avoided committing billions of dollars before the commercial direction of generative AI became clear. But if the company suddenly needs large amounts of capacity, it could be entering the market when chips, memory, electrical equipment and skilled construction labor are more expensive and difficult to obtain.
There is also an execution risk. Apple’s model depends on tightly integrating hardware, software, privacy protections and external AI services into a consumer product that feels reliable. A partnership can provide access to a leading model, but Apple still controls the user experience—and will receive much of the criticism if the resulting assistant is slow, inaccurate or inconsistent.
The company’s next earnings report is expected to bring sharper questions about that balance. Investors will be looking for evidence that Apple can turn AI into stronger device demand or services growth while preserving margins and free cash flow. They will also listen for signs of accelerated spending, new infrastructure commitments or a shift toward larger acquisitions.
Apple’s restraint has clearly spared it from the immediate financial pressure affecting the hyperscalers. Whether it constitutes a durable advantage depends on what happens next. If Apple can use efficient models, custom silicon and outside partnerships to deliver a competitive assistant, it may prove that the industry’s largest infrastructure budgets were not the only route to AI relevance.
If the company’s products require substantially more proprietary computing power, however, the delayed spending could arrive all at once. Apple escaped the first stage of the AI capital-expenditure race. It has not yet demonstrated that it can escape the cost of competing in the market that race is creating.
Leave a Reply