
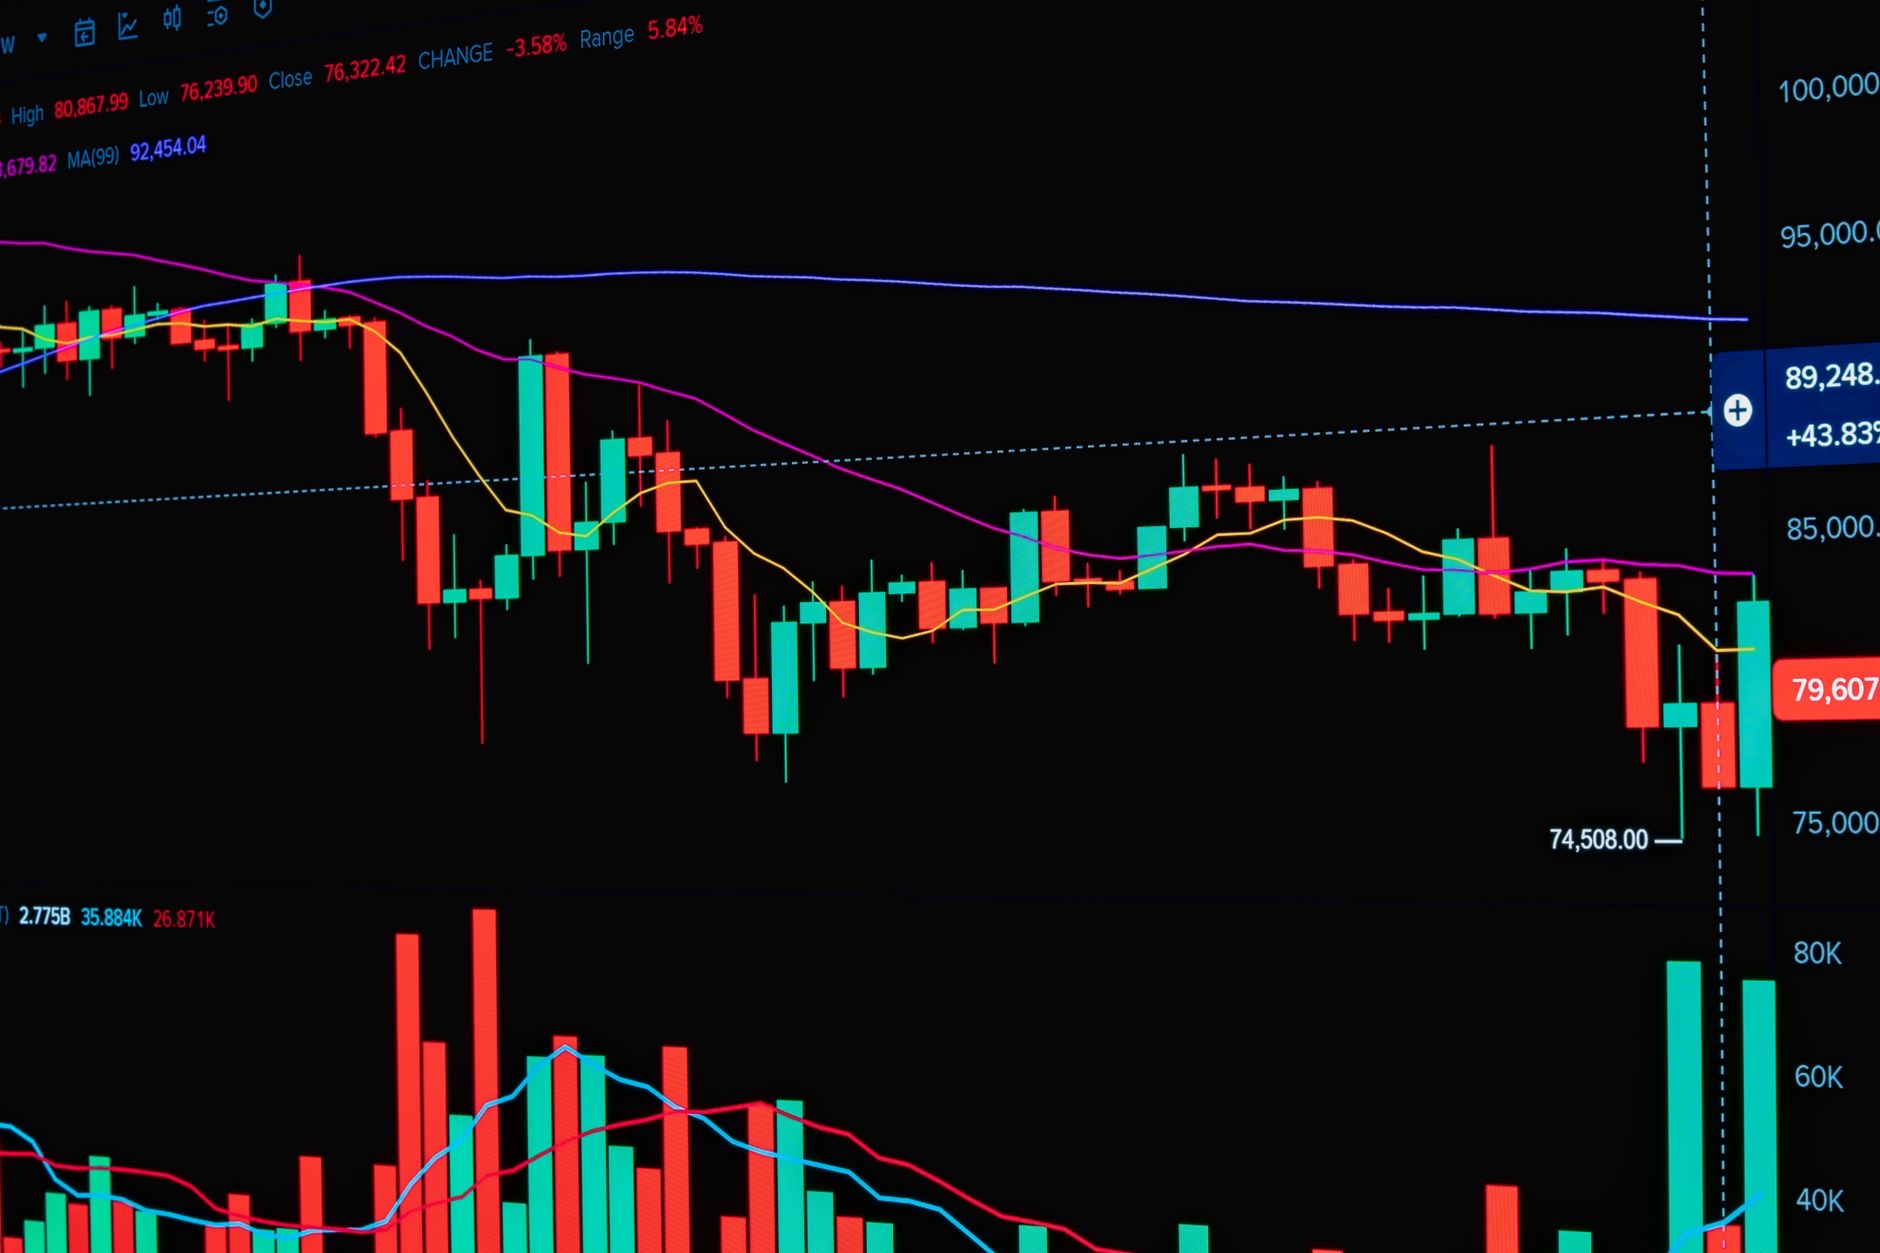
NEW YORK, Nov. 10, 2026 — U.S. stocks finished lower Tuesday after a government report showed consumer prices rose more than economists anticipated in October, sending Treasury yields sharply higher and increasing expectations that the Federal Reserve could deliver a larger interest-rate increase in December.
The S&P 500 declined 29.01 points, or 0.4%, to close at 7,520.93, reversing part of Monday’s strong rebound. The Dow Jones Industrial Average fell 157.86 points, or 0.3%, to 52,231.89, while the technology-heavy Nasdaq Composite dropped 187.26 points, or 0.7%, to 25,065.87. The Russell 2000 index of smaller companies also declined 0.7%, closing at 2,821.38, according to the Associated Press.
The losses followed the release of the October Consumer Price Index by the U.S. Bureau of Labor Statistics. Consumer prices increased 0.4% on a seasonally adjusted basis, slowing from September’s 0.6% increase but exceeding the 0.3% gain economists surveyed by Reuters had forecast. The core index, which excludes volatile food and energy prices, increased 0.3%, compared with expectations of 0.2%.
The figures suggested that inflationary pressure remained persistent despite recent declines in crude oil prices. Core consumer prices have now increased 0.3% in each of the past three months, indicating that price increases have continued across categories beyond energy and food.
The Bureau of Labor Statistics did not publish an overall 12-month inflation rate for October because the federal government funding lapse in October 2025 prevented the collection of survey data needed for many annual comparisons. As a result, investors focused particularly on the monthly changes and their implications for the Federal Reserve’s inflation outlook.
Details of the report showed that housing, food, and energy contributed to October’s price increases. Shelter costs advanced 0.3% and accounted for more than 30% of the monthly increase in the overall consumer price index. Food prices rose 0.5%, including a 0.4% increase in grocery prices and a 0.5% increase in restaurant prices.
Energy prices increased 0.7% after jumping 5.2% in September. Gasoline prices rose 1.0% on a seasonally adjusted basis, while electricity prices increased 0.9%. Other categories also recorded notable increases, including recreation costs, which rose 0.8%, and motor vehicle insurance, which increased 0.7%. Used vehicle prices provided some relief, declining 1.2%.
The inflation figures immediately sharpened the market’s focus on the Federal Reserve’s December 8-9 policy meeting. Before the report was published, Federal Reserve Governor Christopher Waller delivered a speech in London suggesting that policymakers might need to consider stronger monetary tightening if underlying inflation failed to improve.

Waller said he was leaning toward supporting a quarter-percentage-point rate increase in December even if inflation moderated. However, he indicated that a core inflation reading around 0.3% or higher would justify consideration of a half-percentage-point increase. Tuesday’s report matched the threshold he identified, prompting investors to reassess the possibility of a larger move.
Waller’s comments represented his individual policy assessment rather than a decision by the Federal Open Market Committee. Nevertheless, their timing amplified the market reaction because the inflation report offered immediate evidence relevant to his stated concerns. The Federal Reserve is attempting to bring inflation toward its 2% objective while maintaining economic growth and labor-market stability.
Bond markets responded forcefully. The benchmark 10-year U.S. Treasury yield climbed to approximately 4.99%, compared with 4.88% late Monday. Reuters reported that the two-year Treasury yield, which is particularly sensitive to expectations for Federal Reserve policy, rose more than 18 basis points to approximately 4.73%.
Higher Treasury yields can place considerable pressure on equities by increasing the returns available from government bonds and raising financing costs throughout the economy. They also influence mortgage rates, corporate borrowing expenses, and the valuation of companies whose expected profits are concentrated further into the future.
Homebuilding companies were among the market’s notable decliners. Lennar shares fell 5.4%, while D.R. Horton declined 3.8% and PulteGroup dropped 3.9%. Building-materials supplier Builders FirstSource lost 4.6%. Higher borrowing costs threaten housing affordability and can discourage prospective buyers from entering the market, presenting challenges for residential construction businesses.
Technology stocks also faced renewed selling pressure, although company-specific developments contributed to uneven performance across the sector. Nvidia fell 5.5%, becoming the largest individual drag on the S&P 500. The chipmaker has faced additional scrutiny following the announcement of an internal investigation involving its chief executive, Jensen Huang, while investors have also questioned the sustainability of elevated artificial-intelligence valuations.
Other companies connected to artificial intelligence recorded mixed results. GE Vernova declined 3.9%, Micron Technology slipped 1.1%, and cloud infrastructure provider CoreWeave fell 0.5%. However, Broadcom advanced 3.9% and Advanced Micro Devices gained 1.3%, demonstrating that selling pressure was not uniform across the industry.
Investors have become increasingly sensitive to the financing demands of the artificial-intelligence industry’s expansion. Major technology companies are committing substantial capital to data centers, semiconductor equipment, electrical infrastructure, and computing capacity. Higher interest rates could increase the cost of funding these projects and place greater emphasis on how quickly investments generate measurable returns.

Meanwhile, lower crude oil prices provided some relief to financial markets. Brent crude futures declined approximately 1.2% to settle at $91.49 per barrel, while U.S. West Texas Intermediate crude fell 0.9% to $86.04. Oil prices have retreated amid changing expectations about the conflict involving Iran and the risk of further disruptions to Middle Eastern energy supplies.
However, falling oil prices did not prevent Treasury yields from rising following the inflation report. The divergence illustrated how investors distinguished between potential future relief from energy costs and the persistence of price increases already affecting goods and services across the domestic economy.
The U.S. market retreat contrasted with gains in several overseas markets. European shares broadly advanced, while South Korea’s Kospi index jumped 4.4%, supported by strength in major technology companies, including Samsung Electronics and SK Hynix. The mixed international performance reflected differing regional influences alongside the continuing importance of U.S. monetary policy.
Despite Tuesday’s declines, major American stock benchmarks remained higher for the week. The S&P 500 and Nasdaq were each approximately 2% above their previous week’s closing levels, while the Dow had gained 1.8%. The recent fluctuations illustrated the sensitivity of financial markets to economic releases, interest-rate expectations, and developments affecting the technology sector.
Attention now turns to the next economic releases and Federal Reserve communications. The October Producer Price Index is scheduled for November 13, offering another view of inflationary pressure before December’s monetary policy decision. Investors will also monitor corporate earnings and bond-market movements for additional evidence of how companies are responding to higher financing costs.
For households, the implications extend beyond daily market movements. Sustained inflation can erode purchasing power, while higher interest rates can increase the costs of mortgages, automobile financing, and other forms of credit. Businesses may likewise face pressure from more expensive financing and continued increases in operating expenses.
Tuesday’s trading reinforced the importance of incoming inflation data in determining the direction of U.S. financial markets. Although economic growth has remained resilient, investors face renewed uncertainty over how much additional monetary tightening may be necessary and whether corporate earnings can withstand a prolonged period of elevated borrowing costs.
Leave a Reply